
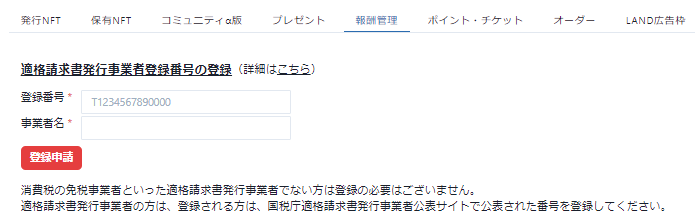
With the invoice system starting on October 1, 2023, we have added a feature for registering your qualified invoice issuer registration number to My Page → Rewards. If you are not a qualified invoice issuer (for example, if you are a business exempt from consumption tax), you do not need to register. If you are a qualified invoice issuer and wish to register, please enter the number published on the National Tax Agency's Qualified Invoice Issuer Publication Site.
Please apply to register your qualified invoice issuer registration number by September 15, 2023. Once we receive your application, we will verify it against the National Tax Agency's Qualified Invoice Issuer Publication Site and, if it is correct, register you as a qualified invoice issuer.
Overview of the invoice system
A qualified invoice is a document, such as an invoice or delivery slip, that contains certain required details so that the seller can accurately inform the buyer of the applicable tax rate, the consumption tax amount and so on. With the start of the invoice system, businesses need a qualified invoice, or documents or data such as a payment notice, in order to claim input tax credits.
Guide to the Qualified Invoice-Based Method (invoice system)
Invoice system special feature
Based on the number you register, we will make payment notices available in the management screen. For questions about the invoice system itself or how to register as a qualified invoice issuer, please contact the National Tax Agency, your local tax office or a tax accountant.
*If you are not a qualified invoice issuer (for example, if you are a business exempt from consumption tax), you do not need to register.
Transactions on HEXA
Because the HEXA site supports credit card payments, whether you pay by credit card or with crypto, buyers transact with Media Equity Inc. (registration number: T1010701037553), the qualified invoice issuer that operates HEXA (Terms of Use (Japanese)). You can therefore use the service with peace of mind, without having to check whether the seller is a qualified invoice issuer.
On the other hand, for sellers, including those reselling on the secondary market, if you are not registered as a qualified invoice issuer, HEXA will be unable to pay consumption tax to you as part of your earnings once the government's transitional measures end (HEXA will instead pay the consumption tax to the tax office). If you are a qualified invoice issuer, please register your registration number (Terms of Use (Japanese)).
How we apply the transitional measures of the invoice system
With the introduction of the invoice system, we can no longer pay consumption tax to those who are not registered for invoices. However, by making use of the system's transitional measures, we will apply the measures below to limit the reduction in your take-home amount to 2%, instead of the full 10% consumption tax.
Transitional period 1 (2023/10/01–2026/09/30)
Using the 80% deduction under the transitional measures, you receive the full 10% consumption tax, but we pay it after deducting a 2% tax-exempt business adjustment fee. This improves your take-home amount by 8% compared with not applying the transitional measures (i.e., not paying the 10% consumption tax).
Transitional period 2 (2026/10/01–2029/09/30)
Using the 50% deduction under the transitional measures, you receive the full 10% consumption tax, but we pay it after deducting a 5% tax-exempt business adjustment fee. This improves your take-home amount by 5% compared with not applying the transitional measures (i.e., not paying the 10% consumption tax).
Transitional period 3 (2029/10/01 onward)
When the government's transitional measures end, you will no longer be able to receive the 10% consumption tax.
*However, the application of the transitional measures may end without notice due to changes in the national system or in the judgment of the tax office or other authorities. In that case, we will be unable to apply the transitional measures and may be unable to pay consumption tax to tax-exempt businesses even during the transitional period.
(For reference) NFT transactions
Transactions in NFTs that do not qualify as crypto-assets are subject to consumption tax. This applies whether you pay in Japanese yen or with crypto. For transactions from October 2023 onward, you must check whether the other party is a qualified invoice issuer in order to claim a consumption tax credit. Rest assured that all transactions on the HEXA NFT Marketplace can be treated as transactions with Media Equity Inc. (HEXA), a qualified invoice issuer.
However, please note that if you withdraw an NFT and trade it by a method that involves no sales intermediary, such as a contract on the blockchain, you must check whether the other party is a qualified invoice issuer in order to claim a consumption tax credit. Please also note that even if the other party provides a registration number, it cannot be treated as that of a qualified invoice issuer unless the number is correctly listed by the National Tax Agency as a qualified invoice issuer.
About the invoice system itself
For details on the invoice system itself, please see the National Tax Agency's page. For inquiries about the invoice system itself, please contact the National Tax Agency's call center.